ArcelorMittal Suspends Ukraine Operations After Strikes Compromise Safety
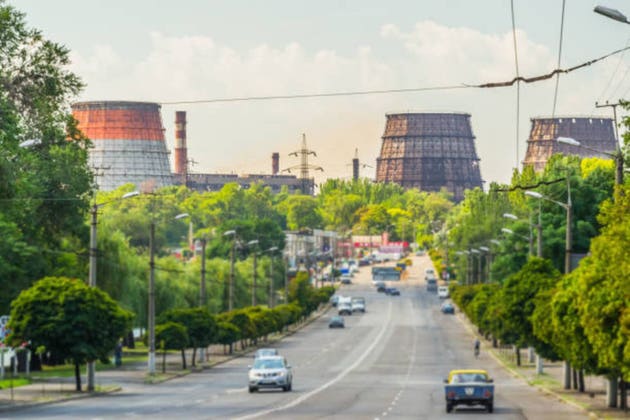
TREE NEWS reports: ArcelorMittal, the world’s second-largest steelmaker, has confirmed it cannot safely resume operations at its Ukrainian facilities following a series of strikes that have damaged infrastructure and endangered workers. The company’s Kryvyi Rih plant, one of Ukraine’s largest industrial assets, remains idle as management assesses the risks of restarting production amid ongoing hostilities.
The announcement marks a significant escalation in the war’s impact on Ukraine’s industrial base. The Kryvyi Rih facility alone accounts for a substantial share of the country’s steel output and directly employs thousands of workers. ArcelorMittal had previously maintained limited operations despite the conflict, but repeated attacks have made even partial production untenable.
Why This Matters for Global Steel and Commodity Markets
Ukraine was a major global steel exporter before the war, shipping millions of tonnes annually to Europe, the Middle East, and Asia. The loss of ArcelorMittal’s output tightens an already constrained European steel market, where energy costs and logistical bottlenecks have curtailed domestic production. Steel prices in Europe could face upward pressure, benefiting producers in Turkey, India, and Brazil that can fill the supply gap.
Iron ore markets may also feel secondary effects. Ukraine is a significant exporter of iron ore concentrate, and reduced mining activity at Kryvyi Rih could lower seaborne supply. However, weak Chinese demand has kept iron ore prices range-bound, limiting the upside from this disruption.
Broader Market Implications
- Equities: ArcelorMittal shares may see modest pressure as investors weigh lost revenue against potential insurance recoveries. European steel peers such as Thyssenkrupp and Voestalpine could benefit from tighter supply and higher prices.
- Commodities: European hot-rolled coil and rebar prices are likely to firm. Iron ore may see a short-lived bounce, but Chinese property weakness remains the dominant driver.
- Currencies: The Ukrainian hryvnia remains under structural pressure, though capital controls limit day-to-day volatility. The euro could see marginal support from higher industrial prices, but the effect is second-order.
- Bonds: Ukraine’s sovereign debt remains distressed and highly sensitive to war developments. Any escalation that further damages industrial capacity raises doubts about reconstruction financing and debt sustainability.
- Crypto: Limited direct impact, though the news reinforces the broader geopolitical risk premium that has occasionally driven flows into bitcoin as a non-sovereign hedge.
Investor Takeaways
This is a reminder that the war in Ukraine continues to reshape European industrial supply chains, with consequences that ripple through commodity and equity markets. Investors with exposure to European steel, construction, and manufacturing should monitor supply tightness and pricing power among surviving producers. The humanitarian and operational risks facing companies with assets in conflict zones also warrant scrutiny — insurance costs, workforce safety, and asset impairment charges can materially affect earnings.
More broadly, the inability to restart a major industrial facility underscores how geopolitical conflict can permanently alter production landscapes. For portfolio construction, this argues for diversification across geographies and sectors, and for maintaining exposure to commodities as a hedge against supply-side shocks.