A Fragmented but Rapidly Maturing Landscape
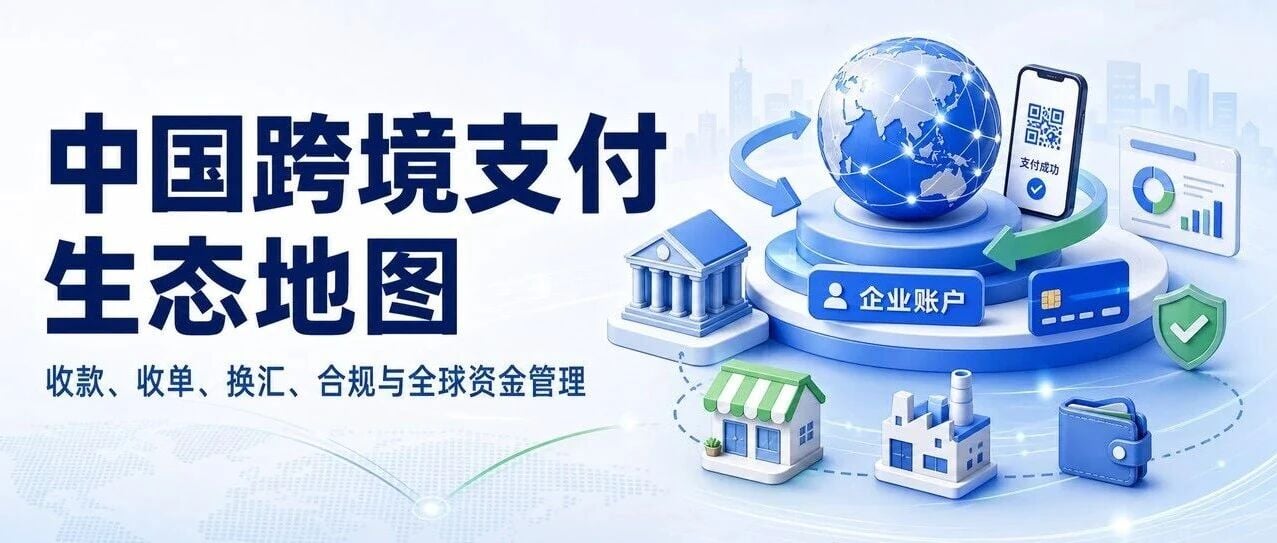
China’s cross-border payment ecosystem has evolved far beyond simple remittance corridors. A new industry map reveals a dense network of players serving Chinese exporters, Amazon sellers, B2B traders, and travel platforms — each solving a distinct piece of the global money movement puzzle. From collection accounts for marketplace sellers to risk-control engines for B2B trade and wallet interoperability for global corporate treasuries, the ecosystem is consolidating around a few core functions: getting money in, sending money out, and managing it across borders.
Three Layers of the Stack
The market can be understood in three layers. First, collection and payout: platforms that help Chinese Amazon and Shopify sellers receive USD and EUR proceeds, then settle into RMB or hold in multi-currency accounts. Second, B2B trade and risk control: services that verify counterparties, screen sanctions exposure, and manage FX for traditional import-export businesses. Third, infrastructure and interoperability: wallet networks, global corporate account providers, and API layers that let fintechs and enterprises plug into cross-border rails without building them from scratch.
- E-commerce collection: Marketplace sellers need fast, low-cost settlement; competition is fierce on FX spreads and payout speed.
- B2B trade finance: Compliance and risk control are the moat; KYC/KYB and sanctions screening are non-negotiable.
- Travel and services: Airlines, OTAs, and travel tech firms need multi-currency acceptance and settlement.
- Wallet and account infrastructure: The layer enabling other fintechs to offer cross-border services.
Why It Matters for Crypto and RWA
Stablecoins and tokenized deposits are increasingly part of this conversation. Chinese payment firms have historically been cautious on crypto, but the underlying demand — instant settlement, 24/7 availability, lower correspondent banking costs — is exactly what stablecoin rails promise. As Hong Kong and other jurisdictions refine licensing for stablecoin issuers, the cross-border payment ecosystem becomes a natural testing ground for tokenized settlement. The players that already own merchant relationships and compliance infrastructure are best positioned to bridge fiat and on-chain rails.
Forward-Looking View
Expect consolidation. The ecosystem is crowded, and margins on pure collection are thin. Winners will be those that combine compliance depth, multi-currency treasury, and API-first distribution. The next 24 months will likely see closer integration between traditional cross-border payment providers and regulated stablecoin infrastructure — not as a replacement, but as a faster settlement layer underneath. For Chinese firms going global, the question is no longer whether they can get paid, but how cheaply, quickly, and compliantly they can move and manage that money.