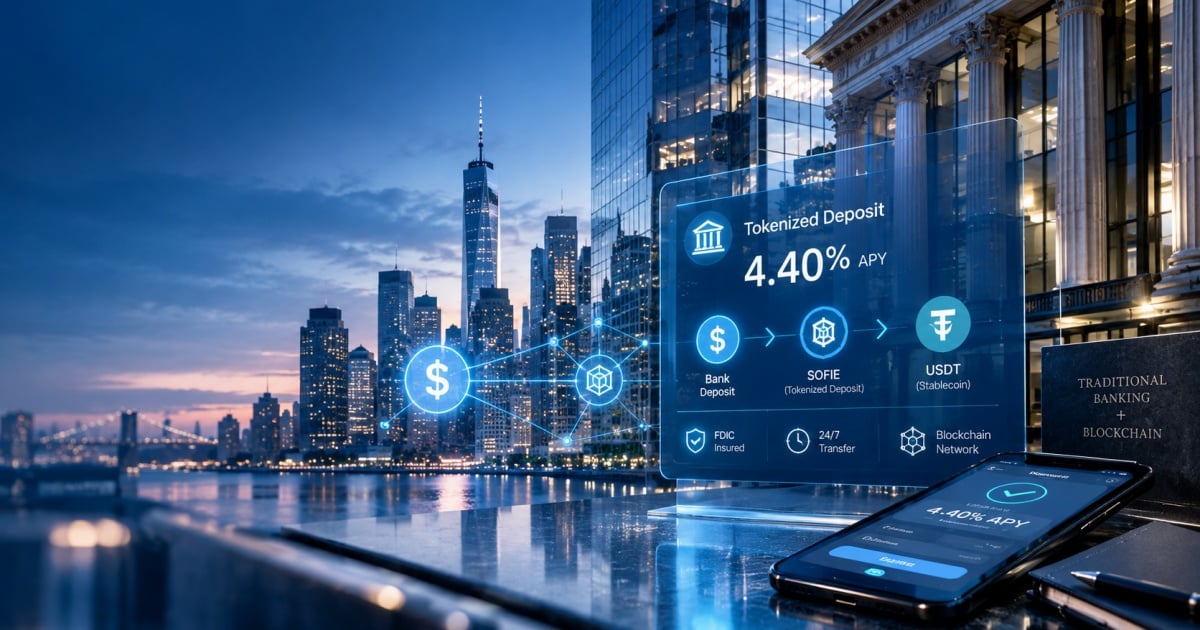
SoFi Enters Tokenized Deposit Market with SOFIE
On October 22, SoFi announced the launch of SoFi Earn (SOFIE), a tokenized deposit product offering a 4.40% annual percentage yield and FDIC deposit insurance for eligible balances. Users can hold interest-bearing tokenized deposits and convert them 1:1 into SoFiUSD, a USD stablecoin, for cryptocurrency trading or on-chain transfers. The product combines yield and liquidity, but its deeper significance lies in banks’ efforts to integrate deposits, payments, and digital asset trading into a unified service framework.
Industry Analysis: Banks’ Strategic Move
Tokenized deposits are emerging as a new pathway for traditional banks to enter the digital asset market. Unlike stablecoins, which are typically issued by non-bank entities and lack direct deposit insurance, tokenized deposits represent direct claims on a bank and can benefit from existing regulatory protections such as FDIC insurance. SoFi’s move signals a shift: banks are no longer content to watch from the sidelines as stablecoins capture liquidity and payment flows. By offering a yield-bearing tokenized deposit that can be converted to a stablecoin, SoFi aims to retain customer funds within its ecosystem while providing the flexibility of blockchain-based transactions.
This development comes as U.S. stablecoin regulation gradually takes shape, with lawmakers and regulators debating frameworks for issuance, reserves, and consumer protection. As the regulatory landscape clarifies, the competition between bank-issued tokenized deposits and non-bank stablecoins is likely to intensify. The key battleground will not just be yield, but who controls the entry and exit points for fund flows and who can build smoother bridges between traditional finance and blockchain networks.
Forward-Looking Perspective
SoFi’s SOFIE could set a precedent for other banks exploring tokenized deposits. If successful, it may accelerate the adoption of tokenized real-world assets (RWAs) and spur further innovation in hybrid financial products. However, challenges remain, including regulatory clarity, interoperability across blockchain networks, and customer education. As banks and stablecoin issuers vie for dominance, the ultimate winners will be those that can offer seamless integration, robust compliance, and compelling yields while maintaining the trust of both traditional and crypto-native users.