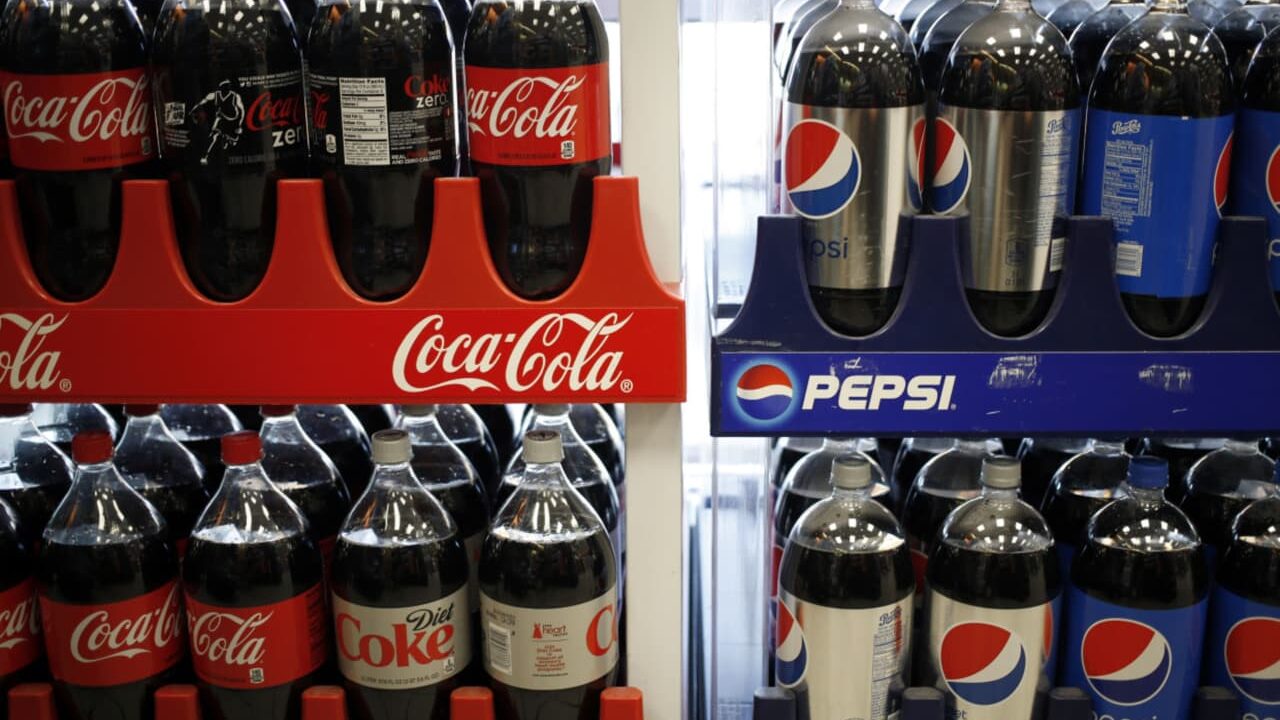
Pepsi Loses Another Pour: KFC Switches to Coca-Cola
TREE NEWS reports: Yum! Brands’ KFC has decided to switch its fountain beverage contract from PepsiCo to Coca-Cola, ending a relationship that dates back decades. The move marks another symbolic — and potentially material — defeat for PepsiCo in the long-running “cola wars,” and it comes as some Wall Street analysts grow more cautious on the snack-and-beverage giant’s outlook.
KFC is one of PepsiCo’s most visible foodservice partners. Losing the account means fewer Pepsi pours at thousands of restaurants globally and, more importantly, a psychological blow in the away-from-home channel, where brand visibility and habit formation are powerful. For Coca-Cola, the win reinforces its dominance in restaurant fountain sales and adds incremental volume to a business that has been steady but not spectacular.
Why This Matters Beyond Two Soda Brands
Fountain contracts are not just about syrup. They are distribution deals that lock in shelf space, marketing dollars, and long-term customer relationships. When a major chain like KFC flips, it signals that Coca-Cola’s sales force and pricing are winning in a channel where PepsiCo has historically been strong. Investors should read this as a competitive share shift, not a one-off headline.
The news lands at an awkward time for PepsiCo. The company has been navigating softer North American beverage volumes, cautious consumer spending, and pressure from GLP-1 weight-loss drugs that some analysts believe could reduce demand for sugary drinks and snacks over time. A high-profile account loss adds to the narrative that PepsiCo’s growth engine is sputtering.
Market Implications
- PepsiCo (PEP): Expect modest downward pressure on sentiment. The direct revenue hit is small relative to PepsiCo’s ~$90 billion top line, but the signal matters. If more restaurant chains follow, estimates for the North America beverage segment could drift lower.
- Coca-Cola (KO): A modest positive. KO shares are often viewed as a defensive staple, and incremental foodservice wins support steady volume growth. Don’t expect a dramatic re-rating from one contract, but it strengthens the bull case.
- Yum! Brands (YUM): Largely neutral. KFC’s beverage switch is an operational decision and unlikely to move the stock meaningfully, though it may slightly improve customer satisfaction if Coke is the preferred brand in key markets.
- Consumer staples sector: Watch for rotation. If PepsiCo’s struggles persist, investors may favor KO, Mondelez, or other staples with cleaner growth stories.
- Broader market: Minimal macro impact. This is a stock-specific story, not a rate or inflation driver.
Context for Investors
The cola wars have always been as much about distribution as about taste. Coca-Cola’s fountain business is a quiet but powerful moat: once a restaurant installs Coke equipment and trains staff, switching costs are real. PepsiCo has countered with its Frito-Lay snack portfolio and aggressive pricing, but in foodservice, Coke’s scale remains formidable.
For long-term investors, the key question is whether this is an isolated loss or the start of a trend. PepsiCo’s management has emphasized innovation, portion control, and health-oriented products to offset soda weakness. If those efforts gain traction, the KFC loss will be a footnote. If not, it could be an early warning sign.
Key Takeaways
- KFC’s switch to Coca-Cola is a symbolic and incremental share win for KO and a sentiment negative for PEP.
- Direct financial impact is small, but the strategic signal in foodservice matters.
- Watch for follow-on account losses or gains — a pattern would be more meaningful than a single contract.
- PepsiCo’s broader challenges — soft volumes, GLP-1 concerns, cautious consumers — remain the bigger story.
- For income and defensive investors, KO’s steady foodservice momentum may look increasingly attractive relative to PEP.
In short, this is not a market-moving event on its own, but it is a useful data point in the slow-burn competition between two of the most widely held consumer staples in the world.