When a Yen-Pegged Stablecoin Broke Its Promise
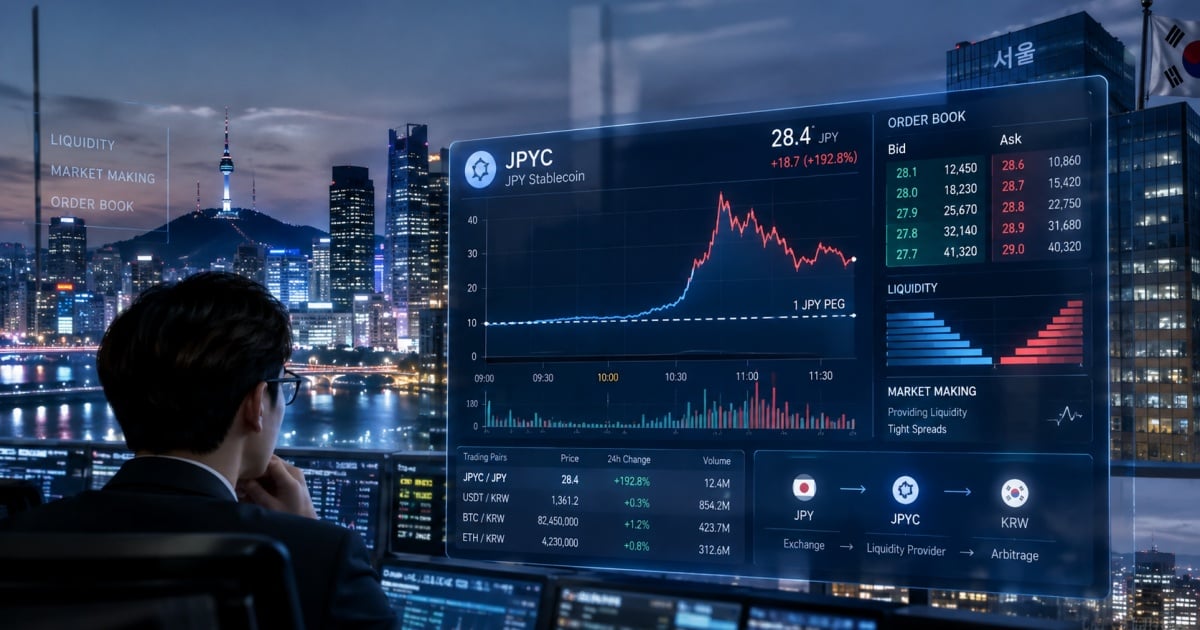
A stablecoin theoretically pegged 1:1 to the Japanese yen deviated from its anchor by several multiples of its target price shortly after listing on a Korean exchange. The episode looks like a localized trading anomaly, but it exposes a structural weakness in cross-border stablecoin circulation that regulators can no longer ignore: price stability depends not only on an issuer’s reserve assets, but also on exchange liquidity, market-making mechanisms, arbitrage channels, and local market rules.
The Peg Is a Market, Not a Number
Stablecoin design literature tends to treat the peg as an accounting problem: hold enough high-quality reserves, publish attestations, and the token trades at par. Reality is messier. A peg is maintained by a continuous arbitrage loop — anyone who can mint or redeem at par, and move tokens cheaply across venues, keeps secondary-market prices in line.
Break any link in that loop and the peg becomes a suggestion rather than a rule:
- Thin order books: A newly listed pair with few market makers can be pushed far from par by modest flow.
- Fragmented venues: If the token trades on one exchange but redeems through another jurisdiction, the arbitrageur faces settlement, FX and compliance friction.
- Redemption gates: Restricted mint/redeem access, banking hours, or KYC bottlenecks slow the corrective trade.
- Local rules: Capital controls, listing standards and market-maker licensing determine who can actually provide two-sided quotes.
In this case, the issuer’s reserves were arguably not the problem. The plumbing was.
Korea Reopens the Market-Making Question
Korea’s Financial Services Commission is revisiting how crypto market making should be regulated. The headline question — whether Korea will formally permit market makers — understates what is really at stake. Korean exchanges have historically relied on informal liquidity providers and incentive programs rather than a licensed market-making regime comparable to traditional securities markets. That gap matters more as stablecoins, including non-USD pegs, proliferate.
For a yen stablecoin, the natural arbitrageur sits in Tokyo, not Seoul. If Korean trading rules, FX conversion costs or corporate account restrictions prevent that arbitrageur from operating efficiently, the Korean price and the Japanese price can drift apart — sometimes dramatically, as observed.
Asia Is Rethinking Stablecoin Market Structure
The broader signal is regional. Japan has moved to formalize stablecoin issuance under its payments framework. Hong Kong is building a licensing regime for issuers. Singapore continues to refine its approach. Korea is now examining the trading layer that connects these regimes.
That is a meaningful shift in regulatory focus: from “who can issue” to “how does it trade, and who keeps it at par?” Reserve transparency remains necessary, but it is not sufficient. Supervisors are beginning to treat market microstructure — liquidity provision, arbitrage access, cross-border settlement — as part of the stability question itself.
What to Watch
- Whether Korea creates a formal market-maker licensing category and what capital and conduct rules apply.
- Whether non-USD stablecoins get dedicated liquidity support or remain peripheral listings.
- How cross-border redemption and FX conversion are handled for arbitrageurs.
- Whether exchanges adopt tighter listing standards for pegged assets.
Stablecoins are often marketed as a solved problem. The yen-peg episode suggests the harder work is just beginning — and that the next wave of stablecoin regulation will be about markets, not just reserves.