MSCI’s Strategy Index Removal: A $2.8B Passive Sell-Off and a Clash of Economic Frameworks
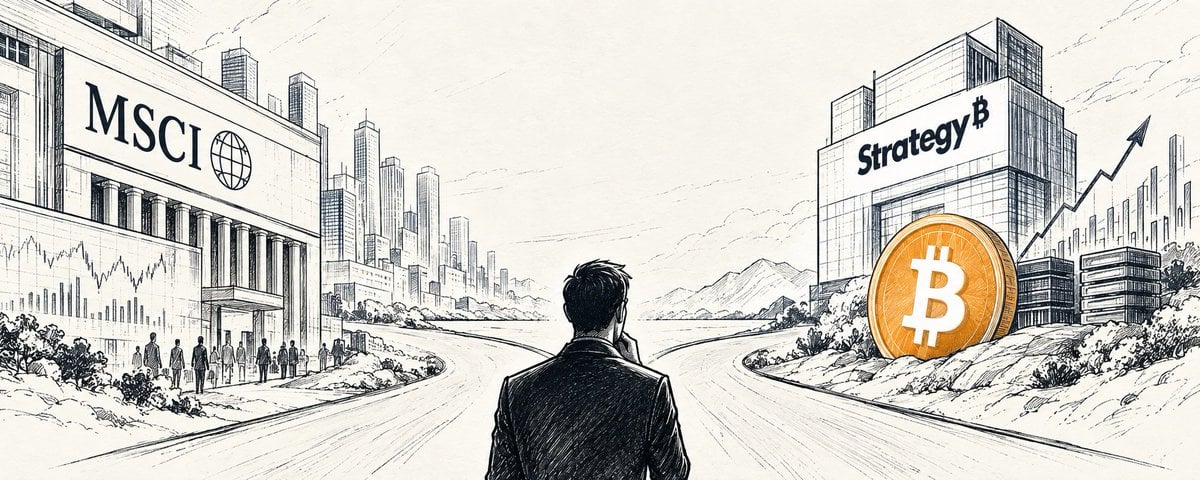
MSCI is considering removing Strategy (formerly MicroStrategy) from some of its indices, a move that could trigger up to $2.8 billion in passive selling. But beyond the immediate capital impact, the decision raises a fundamental question: should a company be defined by what it holds, or by how it creates value? At its core, the bitcoin debate is a head-on collision between the new economy and old frameworks.
Index Rules vs. Corporate Identity
Strategy has transformed from a enterprise software firm into a de facto bitcoin holding vehicle, with its market capitalization now dominated by its BTC treasury. MSCI’s index methodology, however, was built for traditional operating companies, not for entities whose primary asset is a volatile cryptocurrency. Removing Strategy would force passive funds tracking those indices to sell shares, creating a mechanical price shock.
The $2.8 billion estimate underscores how deeply passive investing has become intertwined with crypto exposure. Index inclusion has been a key source of demand for Strategy’s stock, allowing it to raise capital at a premium and accumulate more bitcoin. Any change to that status threatens the flywheel that has powered its strategy.
The Broader Implications
This is not just about one company. It sets a precedent for how traditional finance treats crypto-linked equities. If MSCI excludes Strategy, other index providers may follow, and passive flows could reverse across the sector. It also raises questions about the classification of companies that hold digital assets as their core treasury reserve.
- Passive fund mechanics: Index removal triggers forced selling, regardless of fundamentals.
- Valuation premium: Strategy’s ability to raise capital at a premium could be compromised.
- Precedent risk: Other crypto-treasury companies may face similar scrutiny.
Forward-Looking Perspective
The outcome will depend on how MSCI balances its rules with market reality. A compromise—such as a separate classification for crypto-holding companies—could emerge. But the deeper issue remains: traditional financial frameworks are struggling to accommodate new-economy business models. As more companies adopt bitcoin treasuries, index providers will need to evolve or risk irrelevance. For investors, the lesson is clear: passive exposure to crypto is not as passive as it seems.