US Consumer Sentiment Rebounds in November as Inflation Expectations Plunge
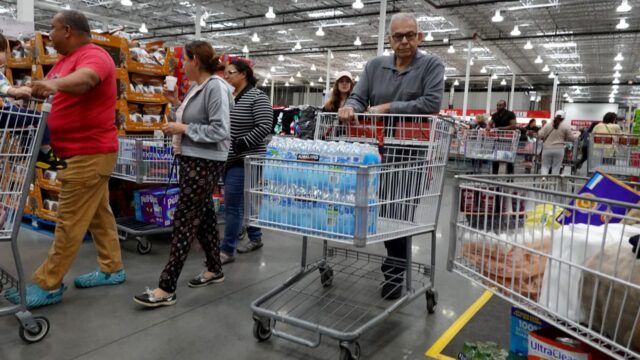
TREE NEWS reports: US consumer confidence rebounded in November, driven by falling gasoline prices, improved expectations for the business environment, and a sharp drop in inflation expectations, signaling that post-election policy expectations are beginning to shape household sentiment.
The University of Michigan’s final consumer sentiment index rose to 51.5 in November from 48 in October, roughly in line with the median forecast of 51.6 in a Bloomberg survey of economists.
Consumers’ inflation expectations for the year ahead tumbled to 3.7% from 4.7% in October, the lowest since February. Longer-term inflation expectations for the next five to ten years also eased. Meanwhile, a sub-index reflecting personal current financial conditions rose to its highest level since July.
Falling gasoline prices were a key support for improved sentiment this month. The national average price per gallon was still above $4 in early November but had fallen to about $3.75 by the end of the University of Michigan’s survey period.
Election Results Lift Expectations, Independent Voters Show Marked Improvement
The survey was conducted from October 20 to November 16, covering the period when US midterm election results were announced. In the elections, Democrats won both the House and Senate and secured governorships in Georgia, Iowa, Texas, Ohio, and Nevada.
Joanne Hsu, the survey’s director, said in a statement that consumers appear to be anticipating possible changes in public policy under a divided government, with the expectations index jumping significantly among independent voters. She also noted that after the election, consumers’ expectations for gasoline prices fell sharply and have “essentially returned to pre-Iran-issue levels.”
High Inflation and High Interest Rates Remain Pressures
Despite the rebound in sentiment, the overall economic pressure on US households has not fundamentally eased. Economists estimate that the October consumer price index rose about 4% year-over-year; since mid-September, 30-year mortgage rates have remained above 7%, keeping borrowing costs elevated.
Persistently rising prices had previously pushed consumer sentiment to historically extreme lows—hitting an all-time low in May and the second-lowest reading on record in October. The economy and cost of living were central issues in the midterm elections, and voter dissatisfaction over high food, gasoline, healthcare, and housing prices partly influenced the election outcome.
Market Implications
The sharp drop in inflation expectations is a welcome development for Federal Reserve officials, who have been closely watching inflation psychology. If expectations continue to decline, it could give the Fed room to slow the pace of interest rate hikes, potentially easing pressure on risk assets.
- Stocks: A moderation in inflation expectations could support equities, particularly growth and technology stocks that are sensitive to interest rates. However, the rebound in sentiment is still weak in absolute terms, and the market may remain volatile as investors digest mixed economic signals.
- Bonds: Falling inflation expectations could lead to lower long-term bond yields, supporting bond prices. But the Fed’s commitment to fighting inflation means short-term rates may stay higher for longer, keeping the yield curve inverted.
- Crypto: Improved risk sentiment could benefit cryptocurrencies, which have been under pressure from tight monetary policy. However, the asset class remains highly sensitive to broader liquidity conditions and regulatory developments.
- Commodities: Lower gasoline prices reflect easing energy costs, which could weigh on oil prices. But supply constraints and geopolitical risks remain.
- Currencies: A less hawkish Fed outlook could weaken the US dollar, but the currency’s direction will also depend on relative economic performance and global risk appetite.
Key Takeaways for Investors
- Inflation expectations are falling, but actual inflation remains high; the Fed is unlikely to pivot quickly.
- Consumer sentiment is improving but remains near historic lows, suggesting the economy is not out of the woods.
- Political gridlock may limit fiscal policy changes, reducing uncertainty for markets.
- Investors should focus on upcoming inflation and employment data for clues on monetary policy direction.