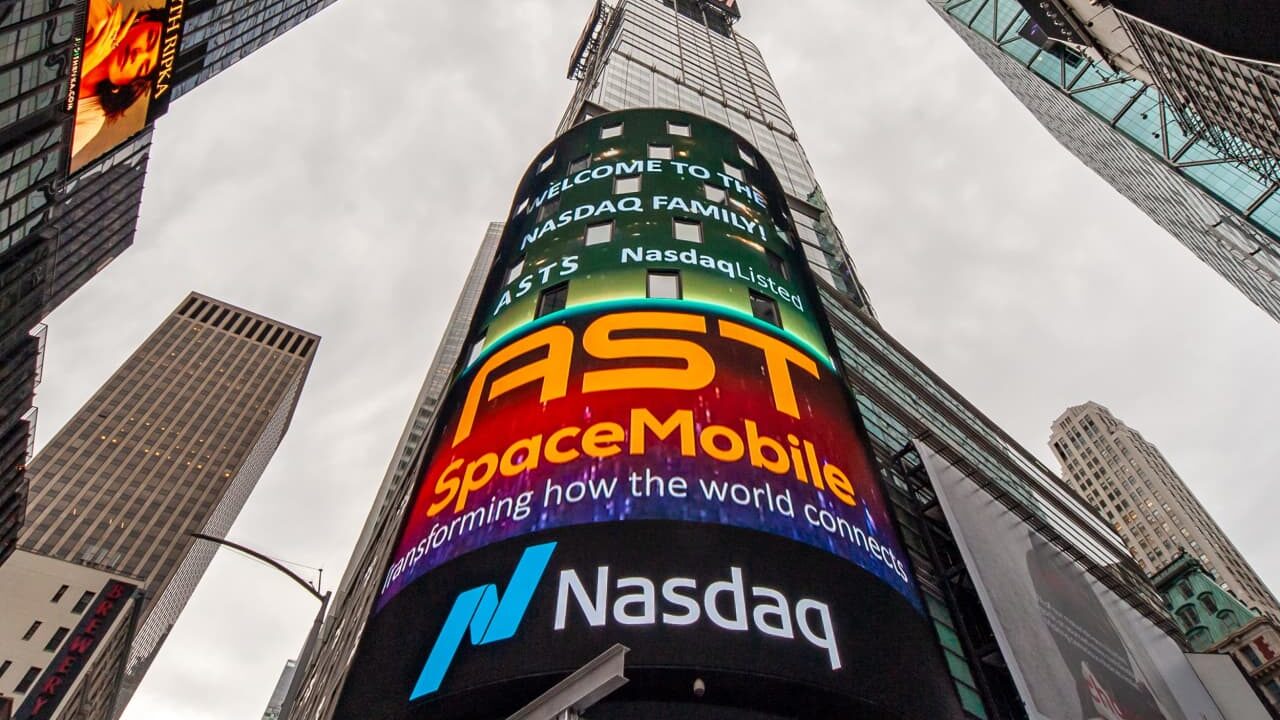
AST SpaceMobile’s Direct-to-Cell Story Meets a Familiar Rival: SpaceX
TREE NEWS reports: AST SpaceMobile shares came under pressure after an analyst warned that the company’s commercial rollout could slip, citing satellite-launch constraints and intensifying competition from SpaceX’s fast-expanding wireless ambitions. The caution lands at an awkward moment for a stock whose entire investment case rests on executing a capital-intensive constellation build on a fixed timeline.
The analyst’s core argument is twofold. First, AST depends on launch partners to place its BlueBird satellites into orbit, and launch capacity is scarce, expensive and shared with far larger programs. Any slip in a launch window cascades into delayed service activation, delayed revenue and a wider funding gap. Second, SpaceX’s Starlink has been steadily pushing into direct-to-cell service through partnerships with terrestrial carriers, which threatens to commoditize the very niche AST is trying to own.
Why the Launch Bottleneck Matters More Than the Headline
Satellite constellations are a scheduling business disguised as a technology business. Revenue only begins when enough satellites are in orbit to provide continuous coverage, and each launch delay pushes out the break-even point. For a pre-revenue or early-revenue company, that means more dilution risk, higher financing costs and a longer window in which competitors can sign exclusive carrier deals.
SpaceX’s advantage is structural rather than merely financial. It owns its launch capability, which means it can iterate faster, absorb failures more cheaply and set its own cadence. Rivals must queue for rides. That asymmetry is precisely what makes the competitive threat credible rather than rhetorical.
Market Implications
- AST SpaceMobile equity: Expect elevated volatility. The bear case is no longer just execution risk — it is execution risk plus a well-capitalized competitor with a cost advantage. Valuation models that assumed a clean ramp now carry a wider discount rate.
- Satellite and space-adjacent equities: The read-across is mixed. Launch providers and component suppliers may benefit from sustained demand, while other direct-to-cell hopefuls face the same competitive overhang.
- Telecom carriers: Carriers gain leverage. With multiple satellite partners competing for spectrum-sharing deals, terrestrial operators can negotiate better terms and avoid being locked into a single vendor.
- Bonds and credit: Space infrastructure is debt-hungry. If launch delays persist, refinancing conditions for speculative-grade space issuers could tighten, widening credit spreads in the sector.
- Crypto and commodities: The direct impact is limited. Indirectly, any sustained risk-off in high-duration growth equities tends to weigh on crypto beta, while satellite demand supports long-run demand for specialty metals and launch materials.
The Bigger Picture
This is not simply a single-stock story. It is a test of whether the direct-to-cell market will be a competitive oligopoly or a SpaceX-dominated utility. Investors have spent years pricing satellite connectivity as a greenfield opportunity. The reality forming now looks more like a capital-intensity contest where launch access, spectrum rights and carrier relationships decide winners long before consumer adoption curves matter.
Key Takeaways for Investors
- Treat launch schedules, not press releases, as the leading indicator for satellite service companies.
- Competitive threats from vertically integrated players deserve a permanent discount in valuation models.
- Watch carrier partnership announcements — they are the clearest signal of who is winning the direct-to-cell race.
- Monitor financing activity. Repeated capital raises at declining valuations are the classic warning sign for pre-revenue space names.
- Position sizing matters more than narrative in this sector; binary timelines make single-name concentration risky.



