CoreWeave’s Debt-Fueled AI Ambitions Rattle Markets as Losses Mount
TREE NEWS reports: CoreWeave, the AI cloud provider that began life as an Ethereum miner, reported second-quarter 2026 revenue of $2.575 billion, up sharply year-over-year, but posted a net loss of $626 million and interest expenses of $640 million. The company’s remaining performance obligations (RPO) stood at $103.7 billion, with revenue backlog at $104 billion. Despite the massive contract pipeline, both its stock and bonds sold off sharply: its 9.625% 2032 bonds now yield over 15%, and shares fell nearly 25% during the week.
From Mining Rigs to AI Clusters
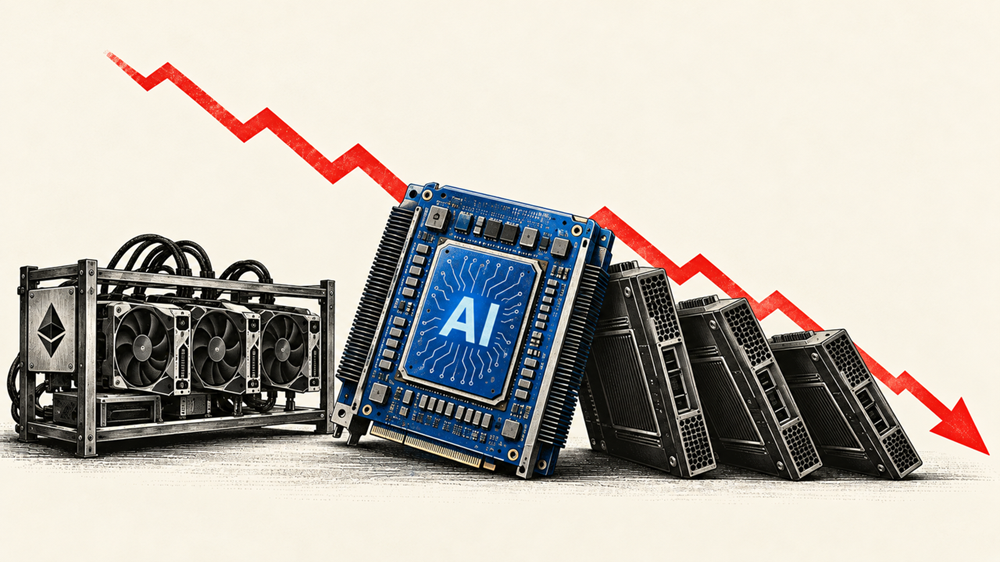
CoreWeave’s transformation from crypto miner to AI infrastructure darling epitomizes the pivot many digital-asset firms have attempted. By repurposing GPU fleets for AI workloads, it secured billion-dollar contracts with Microsoft and other hyperscalers. However, the capital intensity of building AI data centers has forced the company to lean heavily on debt markets, and rising financing costs are now testing investor patience.
The Leverage Conundrum
The widening spread on CoreWeave’s junk-rated debt signals growing skepticism about its ability to service obligations while funding aggressive expansion. Interest expense of $640 million in a single quarter nearly matches its net loss, highlighting how debt servicing is consuming a substantial portion of cash flow. The company’s backlog, while enormous, is concentrated among a few large customers, raising counterparty risk concerns.
- Revenue: $2.575 billion, up year-over-year
- Net loss: $626 million
- Interest expense: $640 million
- RPO: $103.7 billion
- Bond yield: Over 15% on 2032 notes
- Stock decline: Nearly 25% for the week
Broader Implications for AI and Crypto
CoreWeave’s struggles reverberate beyond its own balance sheet. The AI infrastructure trade has been a pillar of market enthusiasm, and any sign of financing stress could trigger a reassessment of valuations across the sector. For crypto-native firms that pivoted to AI, CoreWeave serves as both a blueprint and a cautionary tale: the transition requires deep capital markets access, and the cost of that capital is rising.
Moreover, the company’s origins as an Ethereum miner underscore the cyclical nature of crypto mining economics. When mining margins compressed, CoreWeave diversified into AI—a move that now exposes it to the far larger but more demanding AI infrastructure market.
Forward Outlook
Investors will scrutinize whether CoreWeave can convert its massive backlog into profitable revenue before debt costs overwhelm it. The company may need to raise equity, renegotiate contracts, or slow expansion. With AI capex expectations still elevated, a high-profile stumble could cool sentiment toward the entire AI infrastructure complex—and by extension, crypto-AI crossover plays. The coming quarters will test whether CoreWeave’s bet on AI can outrun its debt burden.