From Digital Asset Trading to Everyday Payments
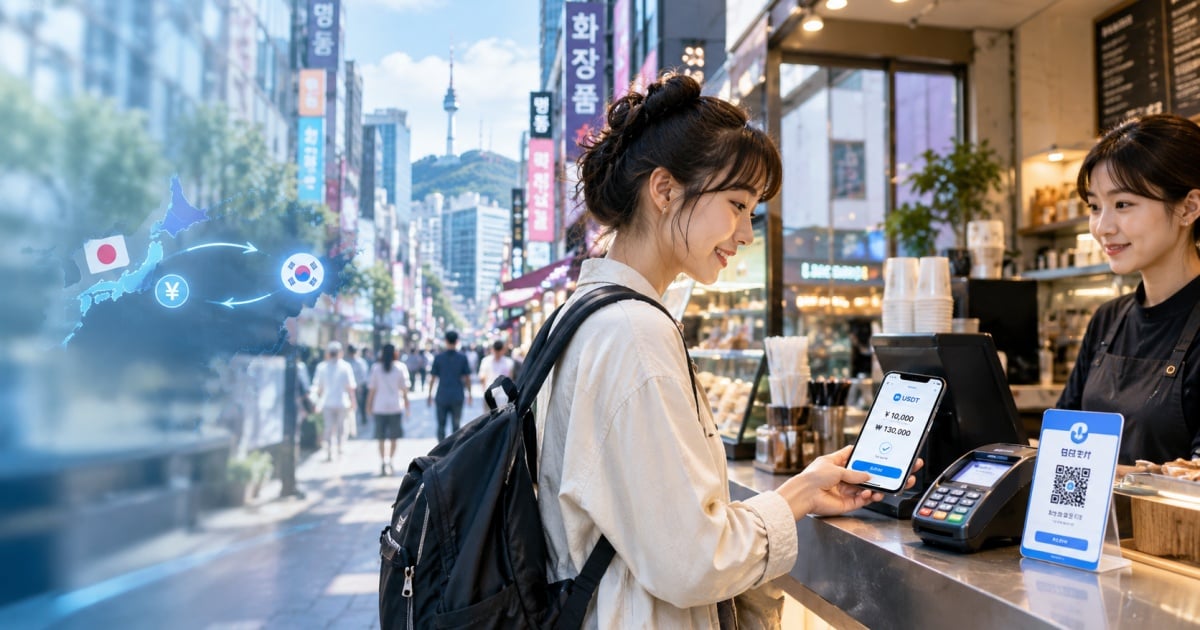
Yen-backed stablecoins are taking a step toward real-world consumer payments. Shinhan Card and SBI Group have launched a proof-of-concept to explore how a yen stablecoin can be embedded into existing card, merchant acquiring, and cross-border settlement infrastructure. The goal is not merely to save Japanese tourists a currency-exchange step when paying in Korea, but to test whether stablecoins can function as a settlement layer within established payment rails.
What the Project Actually Tests
The collaboration focuses on two use cases: tourist card spending and cross-border trade settlement between businesses. For consumers, the promise is a smoother payment experience—no need to convert yen to won at a counter. For merchants and businesses, the appeal lies in faster settlement and potentially lower fees. However, the project remains at the proof-of-concept stage. Key details—including which stablecoin will be used, the foreign-exchange mechanism, fee structure, and commercial timeline—are still undefined.
Industry Implications: Competition Shifts to Payment Channels
The initiative signals a broader shift in the stablecoin market. Until now, competition has largely centered on issuance size and on-chain liquidity. Now, the battleground is extending to payment channels, compliance capabilities, and real transaction scenarios. Stablecoin issuers that can integrate with existing card networks, acquirers, and regulatory frameworks may gain an edge over those focused solely on crypto-native liquidity.
For Japan and Korea, the project also tests whether stablecoins can address longstanding inefficiencies in cross-border payments, which remain slow and costly for small and medium-sized enterprises. If successful, the model could be replicated in other corridors where SBI and Shinhan have presence.
Forward-Looking Perspective
While the concept is promising, significant hurdles remain. Regulatory clarity on stablecoin issuance and cross-border use is still evolving in both Japan and Korea. The project’s success will depend on resolving technical interoperability, FX conversion costs, and merchant adoption incentives. If the proof-of-concept advances to commercialization, it could mark a turning point for stablecoins in Asia—moving them from trading tools to genuine payment infrastructure. For now, the market will watch whether Shinhan and SBI can translate the concept into a scalable, compliant, and cost-effective solution.