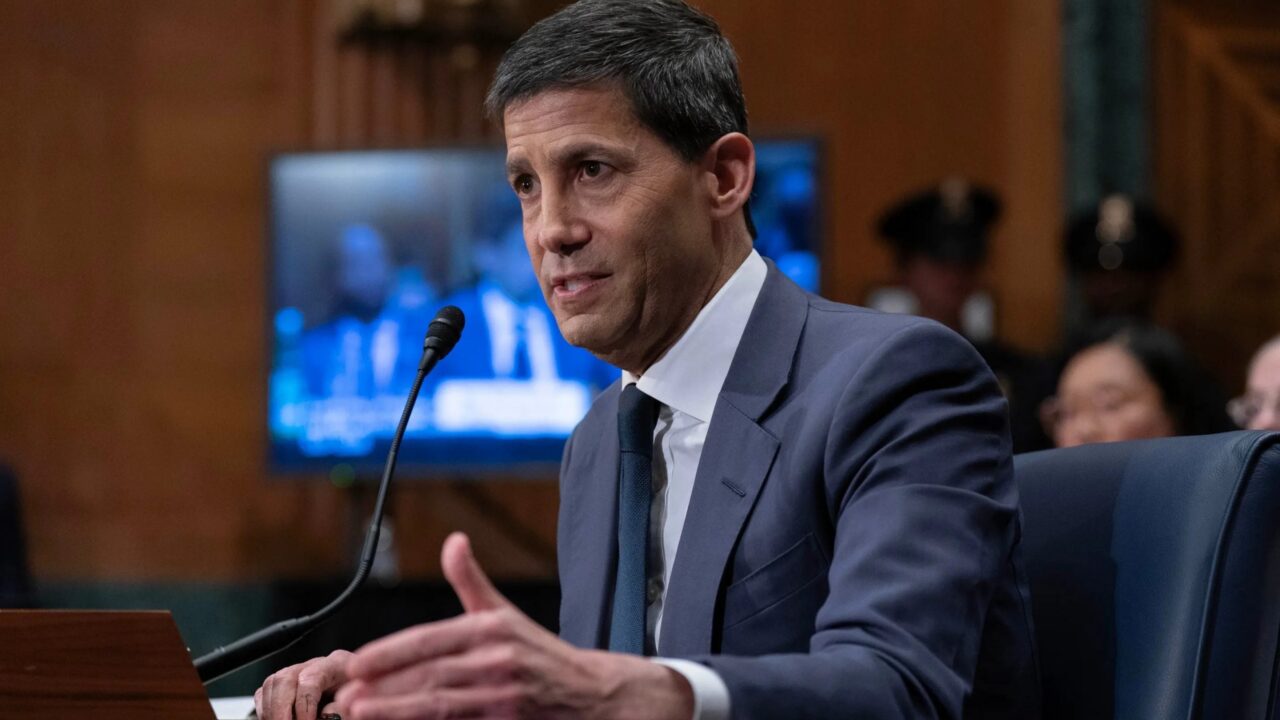
Fed Set to Pause, But Guidance Is the Real Story
TREE NEWS reports: The Federal Open Market Committee (FOMC) is widely expected to keep its benchmark rate unchanged at its meeting this week, following a 25-basis-point hike in September. Markets are pricing only about a 10% chance of a move, but investors are far more focused on how Chair Kevin Warsh will frame the path ahead—especially given his preference for less forward guidance and more data dependence.
Inflation Stays Hot, Housing and Labor Under Pressure
September CPI rose to 3.7% year-over-year on energy prices, while core CPI climbed to 2.6%, still above the Fed’s 2% target and up 0.3 percentage points from August. Mortgage rates above 7% are weighing on housing, and the labor market shows a ‘low layoff, low hiring’ dynamic. This complicates the Fed’s calculus: a pause buys time to assess prior tightening, but persistent inflation may force further hikes.
Warsh’s Communication Challenge
Economists see rising execution risk. Evercore ISI’s Krishna Guha notes the Fed has not clearly explained how it weighs risks to its dual mandate or assesses the degree of tightening. Warsh’s recent remarks in Bangkok were broadly in line with the FOMC mainstream, suggesting a cautious, quarterly hike cadence as a baseline—without pre-committing. A hawkish tone could cement December hike expectations, now above 80%.
Treasury Market Braces for Repricing
Positioning has shifted. Citi strategists flag tactical longs in US and European bonds, and JPMorgan’s survey shows net longs at their highest since early September. Options skew has turned toward calls, with traders paying up to hedge further yield declines. But if Warsh emphasizes persistent inflation and the need for more tightening, these longs could unwind quickly, pushing yields back up. The risk is asymmetric: crowded longs make the market vulnerable to a hawkish surprise.
Forward Look
Even without a rate move, the statement and Warsh’s tone will be pivotal. A hawkish signal likely reinforces December hike bets and pressures bonds; a patient, data-dependent message could sustain the recent rally. With inflation still the key variable, the Fed must demonstrate resolve without locking itself in—a balancing act that will shape rates, the dollar, and risk assets into 2027.