Chinese Police Expose Underground Banking Network Tied to Crypto Laundering
TREE NEWS reports: Authorities in Baotou, Inner Mongolia, have dismantled a criminal network that allegedly operated an underground banking scheme disguised as a free credit-card repayment service, using cryptocurrency to move illicit funds for overseas gambling and telecom fraud operations.
How the Scheme Worked
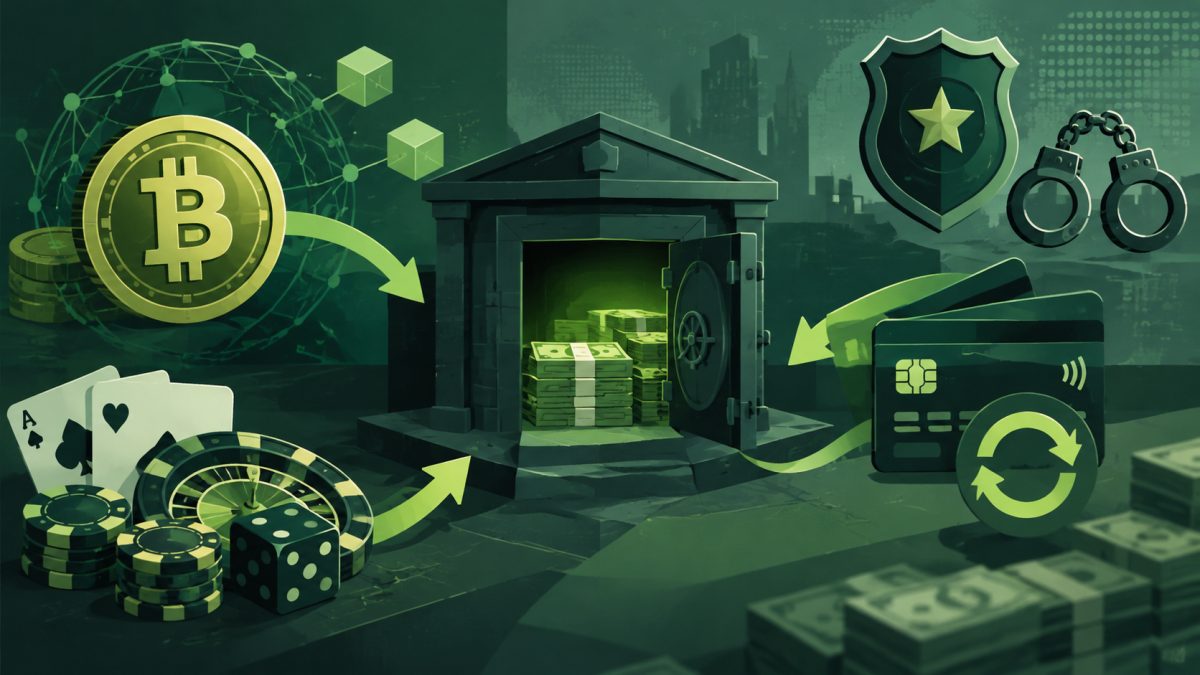
Starting in October 2023, the gang reportedly connected with upstream black and gray industries, including overseas online gambling platforms and telecom fraud rings. Rather than charging customers for credit-card repayment services, the operation used those transactions as a front to pool and transfer illegal capital. Funds were then converted into virtual currencies and routed across borders, obscuring their origin and destination.
- Front service: “Free” credit-card repayment attracted users and generated legitimate-looking transaction flows.
- Upstream links: The network allegedly serviced overseas gambling and telecom fraud operators.
- Laundering channel: Illegal funds were converted to crypto and moved offshore, bypassing traditional banking controls.
Why This Case Matters
The case highlights how underground banks are evolving beyond traditional hawala-style networks. By combining consumer-facing financial services with crypto rails, operators can layer transactions in ways that are harder for banks and payment processors to flag. It also underscores a persistent regulatory concern in China: despite a sweeping ban on crypto trading and related business activities, virtual assets remain attractive for cross-border value transfer because they settle quickly and can be pseudonymous.
Chinese authorities have repeatedly warned that crypto is being used to facilitate gambling, fraud, and capital flight. The Baotou case is likely to reinforce calls for tighter monitoring of payment intermediaries and stricter know-your-customer requirements at the fringes of the financial system.
Forward-Looking Perspective
Expect further enforcement actions targeting the intersection of payment services and crypto settlement. Regulators may push banks and non-bank payment institutions to scrutinize merchant categories such as credit-card repayment and bill payment for abnormal patterns. For the crypto industry, the case is another reminder that compliance and traceability are no longer optional: as law enforcement improves its ability to follow on-chain flows, the window for using virtual assets as an untraceable laundering tool continues to narrow.



