The Hidden Layer Where Cross-Border Payments Are Won or Lost
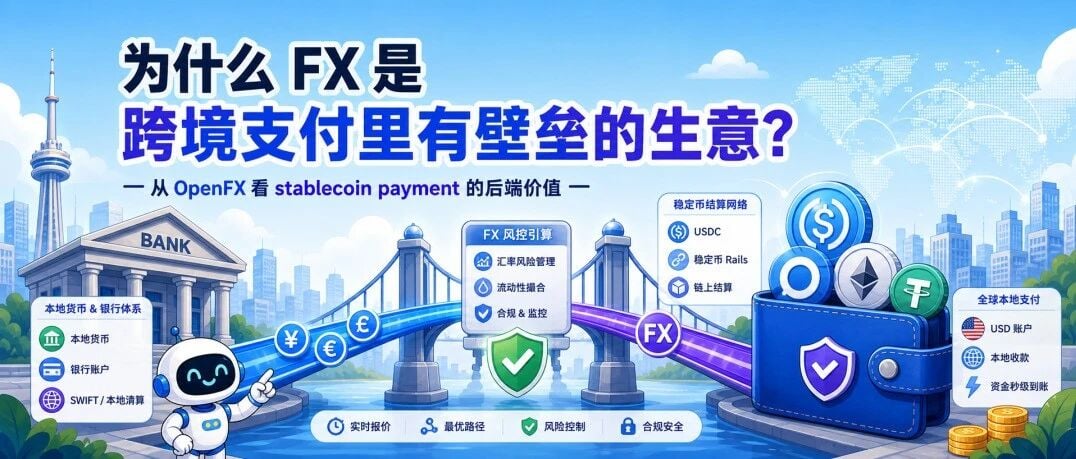
Cross-border payments are often framed as a transfer problem: move money from point A to point B faster and cheaper. In practice, the hard part is not the movement — it is the foreign exchange. OpenFX, a stablecoin-native payment infrastructure provider, is positioning itself not as a simple transfer rail for institutions, but as the layer that absorbs FX risk and liquidity risk, prices that uncertainty, and settles cross-border flows more efficiently using stablecoins.
Why FX Is a Genuine Moat
Payment margins on the transfer itself have compressed toward zero. The durable economics sit in currency conversion, liquidity provisioning, and risk warehousing. To quote a corridor profitably, a provider must hold inventory in both currencies, manage settlement timing across time zones, hedge exposure, and survive volatility spikes. These are balance-sheet businesses, not software businesses.
- Inventory risk: Holding emerging-market currencies exposes providers to devaluation and gap risk.
- Liquidity risk: Thin corridors can gap during stress, forcing providers to source liquidity at unfavorable rates.
- Settlement risk: Legacy correspondent banking adds T+1 to T+3 delays, tying up capital and creating counterparty exposure.
- Pricing uncertainty: Institutions need firm quotes on illiquid pairs, which only players with real risk appetite can offer.
Stablecoins change the backend economics. By settling the funding leg on-chain, providers can reduce the number of intermediaries, compress settlement windows toward near-instant, and free up collateral that would otherwise sit idle in prefunded accounts. That efficiency gain is precisely what lets a firm like OpenFX take on FX risk and still quote tighter than a traditional correspondent chain.
Implications for the Stablecoin Payments Stack
The market has spent years debating whether stablecoins will replace card networks or SWIFT. That framing misses the point. The more defensible opportunity is becoming the risk-taking middle layer: the entity that holds the currency exposure, prices it, and settles it. Front-end wallets and payment apps are commoditizing quickly; the balance-sheet layer is not.
This also reframes competition. Fintechs that treat FX as a pass-through feature will struggle to compete on price in difficult corridors. Firms that treat FX as a core product — with real inventory, hedging, and on-chain settlement — can build durable margins and stickier institutional relationships.
What to Watch
Three developments will determine how this layer evolves. First, whether regulated stablecoin regimes in the US, EU, and Asia give institutions enough legal certainty to hold stablecoin inventory on balance sheet. Second, whether on-chain FX liquidity deepens enough to support institutional-size trades without slippage. Third, whether traditional banks enter the risk-warehousing layer directly or partner with crypto-native specialists.
If stablecoins are the settlement rail, FX is the toll booth. The companies that own the toll booth — not just the road — will capture the most durable value in cross-border payments.



