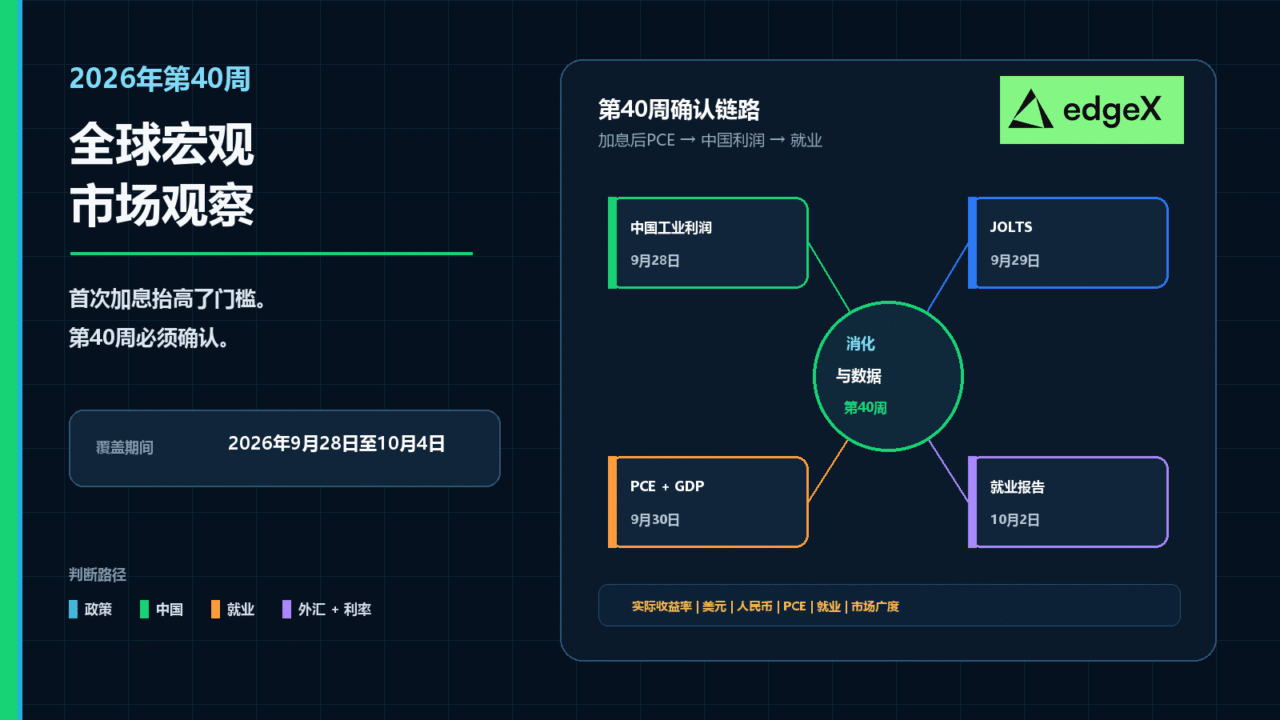
Week 40: The Confirmation Test for a Post-Hike Market
Week 40 is shaping up as a confirmation week for global markets. It follows a stretch in which the Federal Reserve delivered its first rate hike in more than three years, retail demand stayed firm, factory output flatlined, and the Bank of Japan tightened policy once again. The question now is whether the orderly digestion phase that followed that hike can survive a dense data calendar.
The Data Gauntlet
Three releases matter most. First, the August PCE report will show whether inflation remains contained or is re-accelerating. Second, China’s industrial enterprise profits will reveal whether a fresh margin collapse is forcing investors to reprice Chinese growth. Third, official PMI readings will indicate whether the divergence between the factory sector and the household sector is widening or narrowing. The week closes with the September nonfarm payrolls report, which must show labor resilience without reigniting wage fears.
Why It Matters for Crypto and Risk Assets
For digital assets, the transmission channel runs through real yields and the dollar. A hotter core PCE print would push real yields higher, strengthen the dollar, narrow market breadth, and pressure industrial commodities — a combination that historically weighs on bitcoin, ether, and high-beta DeFi tokens. A weaker China profit or PMI reading would add to global growth concerns, hitting cyclical crypto sectors such as mining and infrastructure. A soft or overheated nonfarm payrolls number would complicate the rate path, injecting volatility into funding rates and perpetual futures.
Scenarios to Watch
- Goldilocks: PCE contained, China profits stable, PMI divergence contained, payrolls resilient but not hot. This supports an orderly post-hike digestion and is constructive for risk assets, including crypto.
- Sticky inflation: Core PCE hotter than expected. Real yields stay elevated, the dollar strengthens, and crypto faces a drawdown as liquidity conditions tighten.
- Growth scare: Weak China profits or PMI and a soft payrolls print. Defensive positioning dominates; crypto correlations to tech equities rise.
- Wage scare: Overheated payrolls. Rate-cut expectations get pushed out, pressuring long-duration assets and speculative crypto tokens.
Forward Outlook
Week 40 will not resolve the macro debate, but it will determine whether the post-hike digestion remains orderly or turns into a tightening of financial conditions. For crypto participants, the key is not the headline number but the reaction function: real yields, dollar direction, and market breadth. If those three stay stable, the digestion phase holds and risk appetite can recover into year-end. If not, expect volatility to reassert itself across both traditional and digital markets.