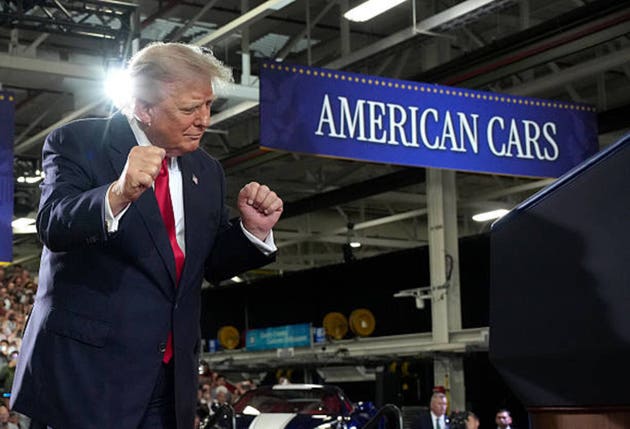
Trump Rolls Back Biden-Era Fuel Economy Standards and EV Mandate
TREE NEWS reports: President Donald Trump has approved a sweeping rollback of federal fuel economy standards and formally terminated the Biden administration’s electric vehicle (EV) mandate, marking one of the most consequential regulatory shifts for the U.S. auto industry in decades. The move dismantles stricter Corporate Average Fuel Economy (CAFE) targets that had been set to tighten through 2030, and removes the regulatory architecture that effectively pushed automakers toward an electrified fleet. The decision lands squarely in the middle of a global auto market already navigating uneven EV demand, heavy capital expenditure commitments, and intensifying competition from Chinese manufacturers.
What Actually Changed
The new standards loosen the annual efficiency improvements required of passenger cars and light trucks, giving manufacturers more runway to sell internal combustion engine (ICE) vehicles and hybrids. By ending the EV mandate, the administration signals that federal policy will no longer penalize automakers for slower electrification. In practice, this reshapes the compliance math for every major automaker: companies that had front-loaded EV investment to meet tightening rules now face a very different cost-benefit calculus, while those with large ICE and hybrid portfolios gain a relative advantage.
Market Implications
Equities: A Rotation Within Autos and Clean Energy
- Legacy automakers with heavy truck and SUV exposure — and slower EV roadmaps — could see near-term margin relief as they avoid costly compliance and can extend the life of profitable ICE platforms.
- Pure-play EV makers face a more challenging narrative. The regulatory tailwind that helped justify premium valuations is weaker, though demand dynamics and product cycles remain the dominant drivers.
- Clean energy and battery supply chains, including charging infrastructure, lithium, and cathode producers, are exposed to a slower-than-expected U.S. adoption curve.
- Hybrid-focused manufacturers are arguably the clearest structural winners, as policy now aligns with consumer preferences that have already shifted toward hybrids.
Bonds and Rates
The macro read-through is modest but not zero. Looser efficiency rules marginally reduce compliance-driven capital spending across the auto sector, a small disinflationary impulse at the margin for vehicle prices and a slight drag on near-term business investment. Neither is large enough to move the Federal Reserve’s reaction function, but they add to the broader deregulatory theme that markets have priced as mildly growth-positive and modestly inflationary over the medium term.
Commodities: Oil Up, Battery Metals Down
- Crude oil gets a structural tailwind. A slower EV transition implies higher long-run gasoline demand than previously modeled, supporting the back end of the crude curve.
- Lithium, cobalt, and nickel face demand-side headwinds as the projected U.S. EV ramp flattens. Prices for battery-grade materials remain sensitive to Chinese supply and could weaken further.
- Natural gas and power see a more mixed picture: slower transport electrification reduces one source of electricity demand growth, though data-center load continues to dominate that story.
Crypto: An Indirect but Real Signal
There is no direct crypto mechanism here, but the policy direction reinforces a broader deregulatory posture that digital-asset markets have read as favorable. Risk assets generally benefit when Washington signals a lighter regulatory touch, and the same political capital driving this rollback is being applied to financial and digital-asset rulemaking. Expect crypto to trade this as part of the wider ‘pro-growth, lighter-regulation’ narrative rather than on its own merits.
Currencies
The dollar impact is second-order. A policy mix tilted toward deregulation and traditional energy can be mildly supportive of U.S. growth expectations, but the FX market is far more focused on rate differentials and trade policy. Watch the Mexican peso and Canadian dollar, given the integrated North American auto supply chain and the potential for cross-border investment shifts.
Key Takeaways for Investors
- Reassess EV exposure. The U.S. policy tailwind for electrification is materially weaker. Companies whose bull case rested on regulatory mandates need a demand-driven story to justify valuations.
- Hybrids and ICE are back in favor. Balance-sheet flexibility and profitable legacy platforms are advantages again.
- Watch the supply chain. Battery materials and charging infrastructure carry elevated policy risk.
- Oil gets a modest structural bid from higher projected gasoline demand.
- Don’t over-trade the macro. This is a sector story first; the rates and FX implications are real but small.
The bigger picture: this is a clear signal that U.S. industrial policy is pivoting away from mandated electrification toward consumer choice and cost. Investors should recalibrate auto-sector positioning accordingly, while treating the macro spillover as a slow-burn theme rather than an immediate catalyst.