Retiree With $400K Equity Weighs Selling Home: A Window Into America’s Locked-Up Housing Market
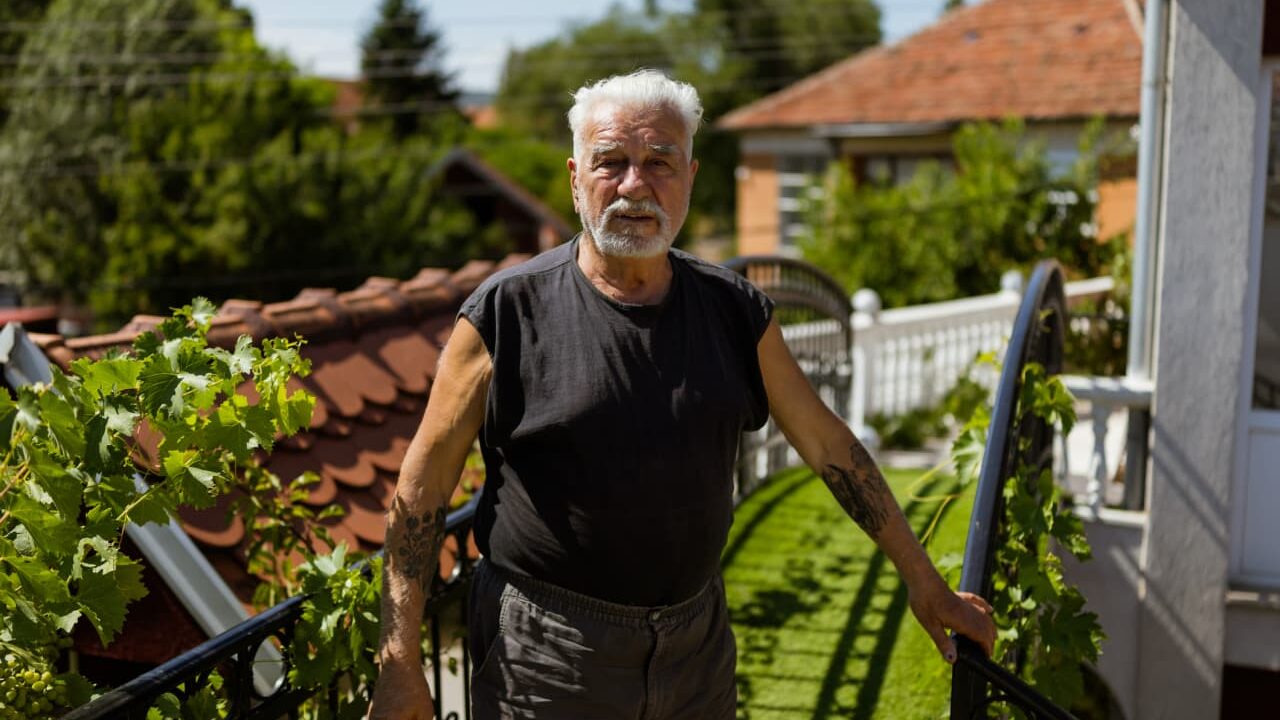
TREE NEWS reports: An 80-year-old homeowner with roughly $400,000 in home equity is asking whether to sell and move because the stairs in their house have become dangerous. The dilemma is a familiar one for older Americans: the advice they have read generally says not to sell, because they hold a low-interest-rate mortgage. The question captures a tension that has quietly reshaped the U.S. housing market — millions of households are sitting on substantial equity but are financially discouraged from selling because giving up a cheap mortgage means financing a new home at today’s much higher rates.
The personal stakes are obvious. Falling on stairs is a leading cause of injury for seniors, and staying in an unsafe home carries real health risks. But the financial math is genuinely complicated, and it is the same math that is distorting the broader housing market.
Why the ‘Lock-In Effect’ Matters
During the pandemic-era low-rate years, a large share of U.S. mortgages were originated at rates between 2% and 4%. With 30-year fixed rates now well above that range, moving means trading a cheap loan for a more expensive one — a monthly payment shock that can run into hundreds or thousands of dollars. Economists call this the mortgage rate lock-in effect. It suppresses existing-home sales, keeps inventory tight, and props up prices even as affordability deteriorates.
For a retiree, the calculus is different from that of a working family. Someone at 80 may not need to finance a new purchase at all, particularly if they downsize, rent, or move to a senior community. Selling could convert illiquid equity into cash that can be invested in Treasury bills, money-market funds, or dividend-paying assets yielding 4% to 5% — a meaningful income stream at today’s rates. That is a striking reversal from the era of near-zero yields, when holding a cheap mortgage and investing elsewhere was often the better trade.
Market Implications
- Housing and homebuilders: Continued lock-in supports prices but starves the resale market. Builders of new homes benefit from the shortage of existing inventory, though high rates still weigh on affordability.
- Rates and bonds: The story is a microcosm of why housing activity is so rate-sensitive. If the Federal Reserve cuts rates, the lock-in effect should gradually loosen, unlocking supply and boosting transaction volumes. That would be a tailwind for mortgage originators, title insurers, and real estate brokerages.
- Consumer spending: Housing wealth is a major driver of household confidence. Seniors who cannot or will not sell may cut back on other spending, while those who do sell could redeploy capital into income-producing assets.
- Equities and crypto: Any release of home equity into financial markets could modestly support demand for yield products, annuities, and even risk assets. But the effect is slow and diffuse, not a market-moving catalyst on its own.
What This Means for Investors
This is not a story about one retiree. It is a story about a structural feature of the post-pandemic economy: high rates have frozen a huge pool of household wealth in place. Investors should watch existing-home sales, mortgage application data, and any signs of Fed easing as the key signals for when that freeze begins to thaw. For older homeowners, the practical takeaway is that the old rule of thumb — never sell a low-rate mortgage — is not universal. When safety, health, and liquidity needs change, the math can flip. A fee-only financial planner and, where needed, a tax advisor can help weigh the trade-offs.
The bottom line: a personal question about dangerous stairs is also a window into the biggest distortion in the U.S. housing market today — and a reminder that household balance sheets, not just central banks, drive the macro cycle.