Micron Signals HBM Shortage Through 2028, Expands at Four Taiwan Fabs
TREE NEWS reports: Micron Technology beat market expectations on both revenue and profit in its latest quarter, but the more consequential disclosure was management’s first explicit guidance that HBM supply will be even tighter in 2027 and 2028 than in 2026. The company is simultaneously expanding high-bandwidth memory capacity across four manufacturing sites in Taiwan: Taoyuan, Taichung, Tongluo, and Tainan.
Micron’s Asia DRAM front-end manufacturing vice president and Taiwan chairman, Dong Huilu, confirmed that AI is driving strong memory demand and that the four-site expansion is proceeding in parallel. Extending the supply-tightness call into 2027–2028 marks the single largest incremental data point from this earnings cycle.
From Cyclical Squeeze to Structural Constraint
The guidance upgrades HBM’s supply constraint from a short-term narrative to a medium-term structural judgment. The direct implication: even with the entire industry expanding capacity, HBM’s pricing strength cycle may run longer than previously expected, and the earnings floor for memory makers extends accordingly.
Micron CEO Sanjay Mehrotra has previously said AI-driven memory demand is pushing supply-demand tightness beyond 2027, with data center customers currently willing to buy roughly 150% of the company’s committable supply — demand exceeding supply by about 50%. New wafer fab construction takes years, and shortages of skilled labor and energy infrastructure make it hard for supply to catch up quickly.
By flagging tighter supply while posting a beat, Micron is effectively endorsing its own expansion logic. It also means downstream AI chipmakers will still face a seller’s market in 2027–2028, with limited bargaining power.
Morgan Stanley Stays Overweight, $1,200 Target
Morgan Stanley noted that Micron’s latest quarter was broadly in line with prior expectations. While sequential improvement decelerated, the business’s resilience remains evident. More importantly, the firm said, Micron extended its supply-demand guidance to 2028 and expects 2027 and 2028 memory supply-demand to be tighter than this year.
Morgan Stanley believes this signal may not be fully priced in by investors in the short term, but it aligns with the bank’s view that AI demand intensity will reshape the memory industry. It maintained an Overweight rating with a $1,200 price target.
Four Taiwan Fabs, HBM4 Ramp
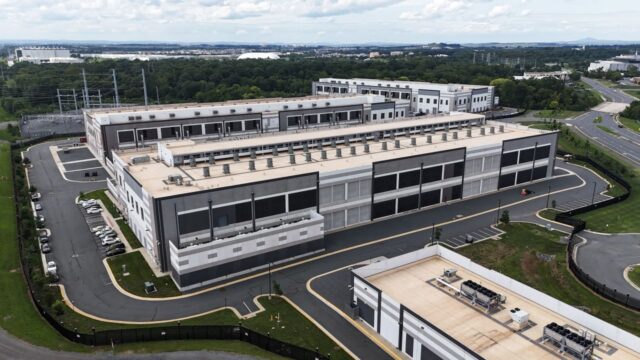
Micron did not disclose per-site expansion scale or production timelines. Taiwan is a key pillar of its HBM expansion. Industry information previously indicated Micron plans to lift HBM monthly capacity to roughly 100,000 wafers by year-end, nearly double last year’s level, with HBM packaging mainly advancing at the Tongluo plant.
In HBM, Micron has long ranked third. Counterpoint Research data showed that in this year’s second quarter, SK Hynix led global HBM share at 50%, Samsung Electronics held 32%, and Micron 18%.
Micron is accelerating its catch-up. Its HBM4 has begun volume shipments for Nvidia’s Vera Rubin platform, with HBM4E mass production planned for next year. It has locked in long-term demand through five-year strategic customer agreements, signing 16 customers by the end of June, and plans capital expenditure above $25 billion for fiscal 2026. If supply is indeed tighter in 2027–2028, customers that lock in capacity early will get priority allocation, potentially lifting Micron’s share ranking.
Key Takeaways for Investors
- Longer pricing cycle: HBM tightness extending to 2028 supports a higher-for-longer earnings base for memory makers and reduces the risk of a sharp pricing rollover.
- Supplier leverage: With demand at roughly 150% of committable supply, memory vendors retain pricing power over AI chip customers through the medium term.
- Watch capex and capacity: Micron’s $25 billion-plus fiscal 2026 capex and four-fab Taiwan expansion are the key variables that could eventually loosen the market.
- Competitive stakes: Micron’s HBM4 ramp for Nvidia and HBM4E plans are the levers that could narrow the gap with SK Hynix and Samsung.
- Pricing risk: Morgan Stanley warns the 2028 guidance may not yet be fully reflected in valuations, leaving room for re-rating if the thesis holds.