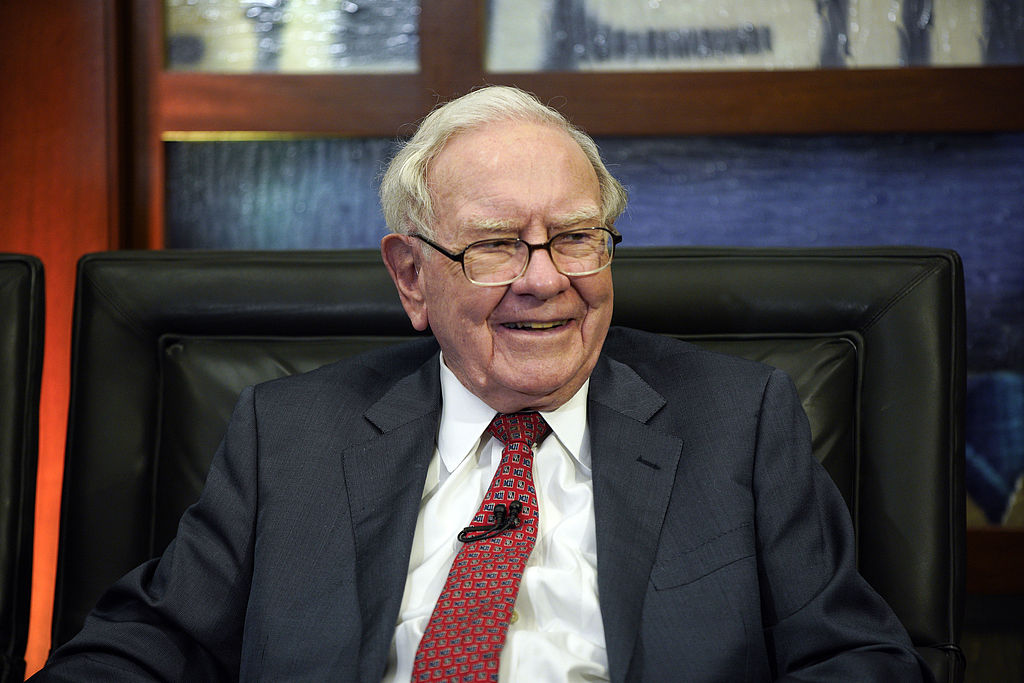
Berkshire Hathaway’s Q3 Earnings: A Tale of Two Trends
Berkshire Hathaway reported a 28% decline in third-quarter net profit, driven by a sharp drop in investment gains that nearly halved from the prior year. Despite the earnings miss, the conglomerate’s cash reserves swelled to a record $377.4 billion, underscoring its defensive posture amid elevated market valuations.
The company also repurchased approximately $9.6 billion of its own stock during the quarter — the highest single-quarter buyback level this year — signaling management’s confidence in Berkshire’s intrinsic value even as it remains cautious on external deployments.
Investment Gains Normalize
The profit decline largely reflects a normalization in investment returns. Berkshire’s equity portfolio, heavily concentrated in Apple, Bank of America, and American Express, generated far smaller gains compared to the prior-year period when markets rallied strongly. With major indices near all-time highs, the company’s unrealized gains have compressed, and mark-to-market accounting amplifies volatility in reported earnings.
Operating earnings, which exclude investment results, remained resilient — a key metric that Warren Buffett has long urged shareholders to focus on. The insurance segment, particularly GEICO, continued to benefit from improved underwriting profitability, while the railroad and energy units delivered steady but unspectacular results.
Cash Hoard Signals Caution
The $377.4 billion cash pile — a record — reflects Berkshire’s difficulty finding attractively priced acquisitions. With interest rates elevated, the company earns meaningful income on its Treasury holdings, reducing the urgency to deploy capital. However, the growing cash balance also raises questions about future capital allocation: will Buffett and his eventual successor, Greg Abel, find compelling opportunities, or will buybacks remain the primary tool for returning capital?
- Buyback boost: $9.6 billion in Q3 repurchases topped any other quarter this year.
- Insurance strength: Underwriting profits offset weaker investment income.
- Succession watch: Greg Abel’s growing role adds a strategic overhang.
Forward-Looking Perspective
Berkshire’s Q3 results paint a picture of a company in wait-and-see mode. The record cash position provides a massive buffer against market downturns but also drags on returns if left idle too long. For investors, the key takeaway is that Berkshire remains a defensive stalwart — but its ability to generate outsized returns hinges on deploying that cash at opportune moments. With equity markets stretched and geopolitical risks simmering, patience may prove prudent, but shareholders will eventually demand action.