China’s Battery Export Machine Keeps Rolling — Just Not Toward America
TREE NEWS reports: China’s lithium battery exports rose 36.4% year-on-year in the first three quarters of 2025, customs data showed on October 14, extending a run of double-digit growth even as shipments to the United States collapsed. Over the first eight months, export value to the U.S. fell 24%, while exports to every other market combined climbed roughly 53% on a comparable basis — more than filling the hole left by American demand.
The shift is more than a trade statistic. It reflects a structural re-routing of the global battery supply chain, with Chinese manufacturers deepening ties across Europe, Asia, Latin America and the Middle East through joint ventures, local plants and long-term service contracts.
Who Is Winning the Overseas Race
Regional demand divergence is redrawing competitive lines. In the first eight months of the year, CATL’s share of the ex-China EV battery market rose to 33.7% from 29%, helped by steady European growth and rapid gains in Asia. South Korea’s LG Energy Solution, SK On and Samsung SDI saw their combined overseas share fall to 26.8% from 37.9%, dragged down by weakening North American demand.
BYD illustrates the split between home and abroad. Its global battery share slipped to 15.1% from 17.1%, yet its overseas share climbed to 11% from 8.2% as its own vehicle exports pulled battery installations into Europe, Asia and South America. Smaller players are climbing too: Gotion High-Tech doubled its overseas share to 4%, EVE Energy rose to 2.1% from 0.9%, and Honeycomb Energy and CALB both gained ground.
From Supplier to Co-Investor
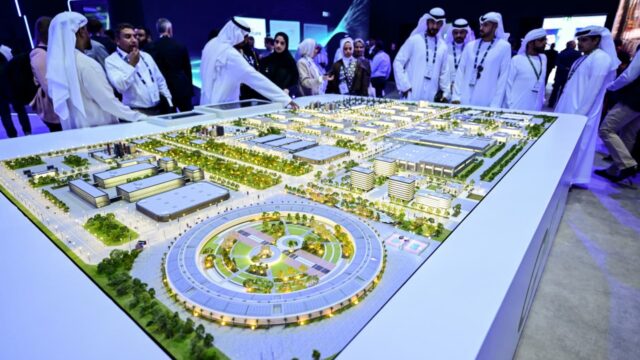
The model is changing. Volkswagen and Gotion are negotiating a joint venture in Spain under which Gotion would invest about €1.1 billion for a 49% stake, subject to approval, aimed at adding LFP supply for mainstream models — a segment Europe lacks at scale. Elsewhere, local delivery, commissioning, maintenance and even end-of-life recycling are being written into contracts. Storage is the other growth engine: CATL, EVE, BYD, Hithium and Great Power led overseas energy-storage cell shipments in the first half, with EVE and Great Power boosted by residential storage demand.
Market Implications
- Equities: Chinese battery and storage names with genuine overseas footprints — CATL, BYD, EVE, Gotion — gain a structural growth narrative that is decoupled from U.S. tariffs. Korean battery makers face continued estimate cuts as North American EV demand softens.
- Commodities: Sustained LFP and storage-cell demand supports lithium, iron phosphate and graphite volumes, though prices remain hostage to oversupply. European plant build-outs imply rising demand for construction and industrial metals.
- FX and rates: Large outbound capex and euro-denominated JV commitments add to China’s overseas direct investment flows, a mild drag on the yuan at the margin and a tailwind for euro-area industrial investment.
- Policy risk: The U.S. remains the key wildcard. Further tariff escalation or rules targeting Chinese-owned plants in third countries could slow the very joint ventures now driving growth.
Key Takeaways for Investors
First, the China battery story is no longer a U.S. story — diversification has worked, and investors should value overseas share, not just headline export growth. Second, capital intensity is rising: co-investment and local service obligations mean larger balance-sheet commitments and slower payback, so cash flow discipline matters more than order announcements. Third, execution risk is uneven — some overseas plants are ramping, others are delayed by demand shifts. Finally, watch storage, where repeat orders from global developers offer more durable revenue than one-off EV contracts.