Tokenized Stocks Boom: Issuers Struggle to Profit as Value Shifts to Apps and Collateral
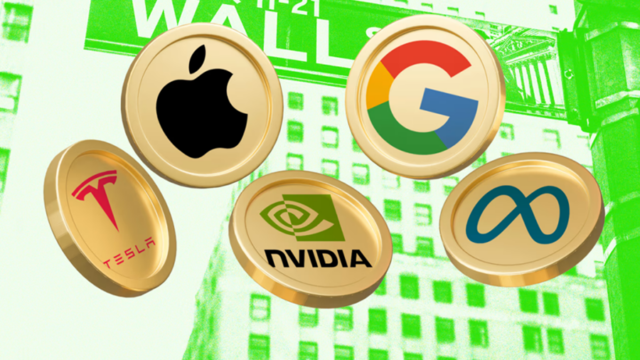
TREE NEWS reports: Tokenized stocks are gaining traction, but the economics are upside down: the companies minting the tokens are barely making money, while the real profits accrue to applications that use them and to those who accept them as collateral. The model relies on arbitrageurs who mint tokens when the on-chain price trades at a premium and redeem when it trades at a discount, keeping prices anchored to the underlying shares.
Who Mints, Who Sells, Who Profits
Different issuers set different rules on who can mint, where tokens can be sold, and what holders can do with them. All of them source actual shares through Alpaca, the US brokerage API. Exchanges like Binance, Robinhood, and Coinbase own their own venues and distribute tokens directly to their own customers. That gives them control over distribution but also caps the upside for the issuers themselves, who operate more like infrastructure providers.
The more interesting development is composability. Once a tokenized stock exists on-chain, it can be used in lending protocols, as collateral, or in structured products. This financialization makes credit cheaper and more accessible, but it also introduces new layers of risk. The profits flow to those who build applications on top of the tokens, not to those who mint them.
Arbitrage: The Hidden Engine
Arbitrageurs play a crucial role. When a token trades above the underlying stock, they mint new tokens and sell them; when it trades below, they buy and redeem. This keeps prices in line but requires capital and operational sophistication. The minting process is permissioned, and not everyone can participate. That creates a moat for those with access, but it also limits the supply response.
For now, the tokenized stock market remains small relative to traditional equities, but the infrastructure is being built. The key question is whether issuers can capture more value as the market grows, or whether they remain commoditized pipes for applications and collateral users.
Forward Look
As regulatory clarity improves and more assets are tokenized, the battle will shift to distribution and composability. Issuers that can offer better minting terms, broader collateral acceptance, and deeper integration with DeFi may capture more of the value chain. But if history is any guide, the application layer and collateral markets will continue to capture the lion’s share of profits.