US Existing Home Sales Plunge to 16-Year Low as High Rates and Inflation Crush Demand
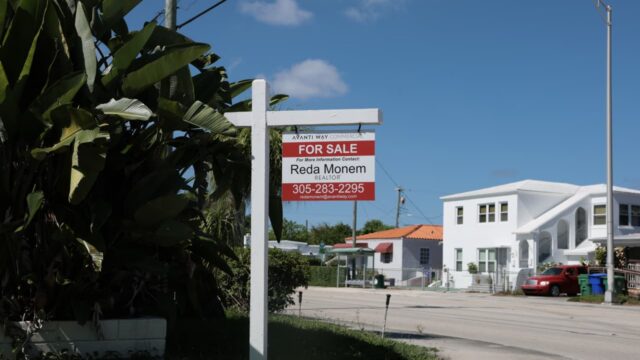
TREE NEWS reports: Existing home sales in the United States fell to their lowest level in 16 years in October, as mortgage rates above 7% and persistent inflation kept prospective buyers on the sidelines. The National Association of Realtors (NAR) reported Thursday that sales of previously owned homes dropped 5.5% month-over-month to a seasonally adjusted annual rate of 3.75 million units, the weakest pace since 2010. Sales in the West tumbled to the lowest level since records began in 1999, while the South and Midwest also hit more than decade lows.
The slump underscores the deep freeze in the housing market, where affordability has deteriorated sharply. The NAR’s housing affordability index, which measures whether a typical family can qualify for a mortgage on a median-priced home, has fallen to its lowest level since mid-2025. Housing costs also emerged as a key issue in this week’s midterm elections, reflecting growing voter anxiety over the cost of living.
Market Implications
The housing data paints a picture of a sector caught between high borrowing costs and still-elevated prices, with significant spillovers for financial markets.
- Stocks: Homebuilders and related sectors could face pressure as demand weakens, but the data also reinforces expectations that the Federal Reserve may be nearing the end of its rate-hiking cycle. A potential peak in rates could lift builder sentiment and spark a relief rally in rate-sensitive stocks, including utilities and real estate investment trusts (REITs).
- Bonds: The weak sales figures support the case for lower long-term yields, as investors bet on a slowing economy and a more dovish Fed. Treasury prices may rise, pushing yields down, especially if upcoming inflation data confirm a cooling trend.
- Crypto: Risk assets like cryptocurrencies could benefit from a softening rate outlook, as lower yields reduce the opportunity cost of holding non-yielding assets. Bitcoin and other digital tokens often trade as proxies for liquidity conditions and risk appetite.
- Commodities: Weaker housing activity implies reduced demand for construction materials such as copper and lumber, potentially weighing on industrial metals. However, if rate cuts materialize, a rebound in housing could revive demand later in 2026.
- Currencies: The dollar may soften if the data accelerate expectations of Fed rate cuts, though safe-haven flows could provide support amid global uncertainty.
Supply Shows Signs of Thawing
There are tentative signs of easing on the supply side. Inventory of unsold homes rose 4.6% year-over-year to 1.59 million units, the highest for any October since 2019. At the current sales pace, that represents 5.1 months of supply, the most since late 2015. The median existing-home price edged up just 0.4% from a year earlier to $416,700, the smallest annual gain since February, indicating that price growth is losing momentum.
Price cuts are becoming more common. Redfin reported that 36% of homes sold last month had at least one price reduction, the highest share on record for the platform. Sales of existing condos and co-ops fell to the lowest level since 1999, highlighting weakness across segments.
NAR Chief Economist Lawrence Yun noted that despite steady job growth, sales remain depressed, and that a decline in mortgage rates could unleash substantial pent-up demand. “Given the sustained job market growth, the current pace of home sales is unusually low,” Yun said. “Once mortgage rates move lower, the release of suppressed demand could be sizable.”
Separately, weekly jobless claims rose to 200,000 but remain historically low, suggesting the labor market has not yet deteriorated significantly.
Key Takeaways for Investors
- Housing weakness is a symptom of the broader high-rate environment; watch for Fed signals that could trigger a shift in rate expectations.
- Rate-sensitive sectors such as homebuilders, REITs, and utilities may see volatility, with potential upside if rates peak.
- Bond markets are likely to price in slower growth, supporting Treasuries; monitor inflation data for confirmation.
- Commodities tied to housing, like copper and lumber, face near-term headwinds but could rebound if affordability improves.
- Crypto and risk assets may benefit from a more accommodative monetary policy stance, but remain sensitive to broader risk sentiment.